
Rangunwala Academy
Modified Golden Rules of Accounting
Modification in the Golden Rules for Debiting & Crediting the Accounts in Double Entry Accounting System for Better Understanding
A logical framework for debit and credit
The Modified Golden Rules of Accounting are designed to make double-entry accounting easier to understand and apply. They retain the discipline of double entry while clarifying the situations that frequently confuse beginners—especially the difference between a receiver and a receivable, a giver and a payable, and the movement or changing value of property.
Every business transaction affects at least two accounts. The correct entry is reached by understanding the transaction, identifying those accounts, classifying each account and then applying the relevant rule.
Why were the Golden Rules modified?
Traditional wording is useful, but students may still face uncertainty when an account represents an amount receivable or payable, when property does not physically move but its value changes, or when a transaction is settled through another person. The modified wording makes these conditions explicit.
The Modified Golden Rules
1. Personal Accounts
Debit: receiver or receivable from them.
Credit: giver or payable to them.
This wording distinguishes the person who receives now from the amount that is receivable from that person, and the person who gives now from the amount that is payable to that person.
2. Real Accounts
Debit: when property comes in or its value increases.
Credit: when property goes out or its value decreases.
The value-based wording covers transactions where property remains in the business but its recorded value changes.
3. Nominal Accounts
Debit: all expenses and losses.
Credit: all incomes and gains.
The traditional rule already expresses the required logic clearly, so its substance remains unchanged.
Goods within this framework: Purchases, Sales, Purchase Returns, Sales Returns, Opening Stock, Closing Stock and other goods-related accounts are classified as Real Accounts because they represent goods or changes in the value of goods.
Traditional wording and the modified wording
| Account type | Traditional rule | Modified clarification |
|---|---|---|
| Personal | Debit the receiver; credit the giver. | Debit the receiver or receivable from them; credit the giver or payable to them. |
| Real | Debit what comes in; credit what goes out. | Debit when property comes in or value increases; credit when property goes out or value decreases. |
| Nominal | Debit expenses and losses; credit incomes and gains. | No substantive change is required. |
How to identify and record a transaction
Practical journal-entry examples
1. Furniture purchased for cash — ₹20,000
Furniture is a Real Account whose value increases, so it is debited. Cash is a Real Account that goes out, so it is credited.
Furniture A/c Dr. ₹20,000
To Cash A/c ₹20,000
2. Goods purchased on credit from Asha Traders — ₹30,000
Purchases represents goods coming in, so it is debited under the Real Account rule used in this framework. The amount is payable to Asha Traders, so the Personal Account is credited.
Purchases A/c Dr. ₹30,000
To Asha Traders A/c ₹30,000
3. Goods sold on credit to Rehan — ₹40,000
The amount is receivable from Rehan, so his Personal Account is debited. Sales represents goods going out, so it is credited.
Rehan A/c Dr. ₹40,000
To Sales A/c ₹40,000
4. Amount paid to Asha Traders — ₹15,000
Asha Traders receives the payment and the amount payable to them decreases, so the Personal Account is debited. Cash goes out, so the Real Account is credited.
Asha Traders A/c Dr. ₹15,000
To Cash A/c ₹15,000
5. Salary paid — ₹10,000
Salary is an expense, so the Nominal Account is debited. Cash goes out, so the Real Account is credited.
Salary A/c Dr. ₹10,000
To Cash A/c ₹10,000
6. Commission received — ₹5,000
Cash comes in, so the Real Account is debited. Commission is income, so the Nominal Account is credited.
Cash A/c Dr. ₹5,000
To Commission A/c ₹5,000
Benefits for students and teachers
- Clarifies the difference between a receiver and a receivable.
- Clarifies the difference between a giver and a payable.
- Covers both physical movement and changes in the value of property.
- Creates a consistent reasoning process for journal entries.
- Helps teachers explain why an account is debited or credited.
- Builds the foundation for Ledger, Trial Balance and Final Accounts.
Official registration details
Copyright Registration
- Title
- Modification in the Golden Rules for Debiting & Crediting the Accounts in Double Entry Accounting System for Better Understanding
- Author
- Ejaj Abubakar Rangunwala
- Registration No.
- L-99471/2021
- Registration date
- 15 February 2021
- Authority
- Government of India
- Brand
- Rangunwala Academy
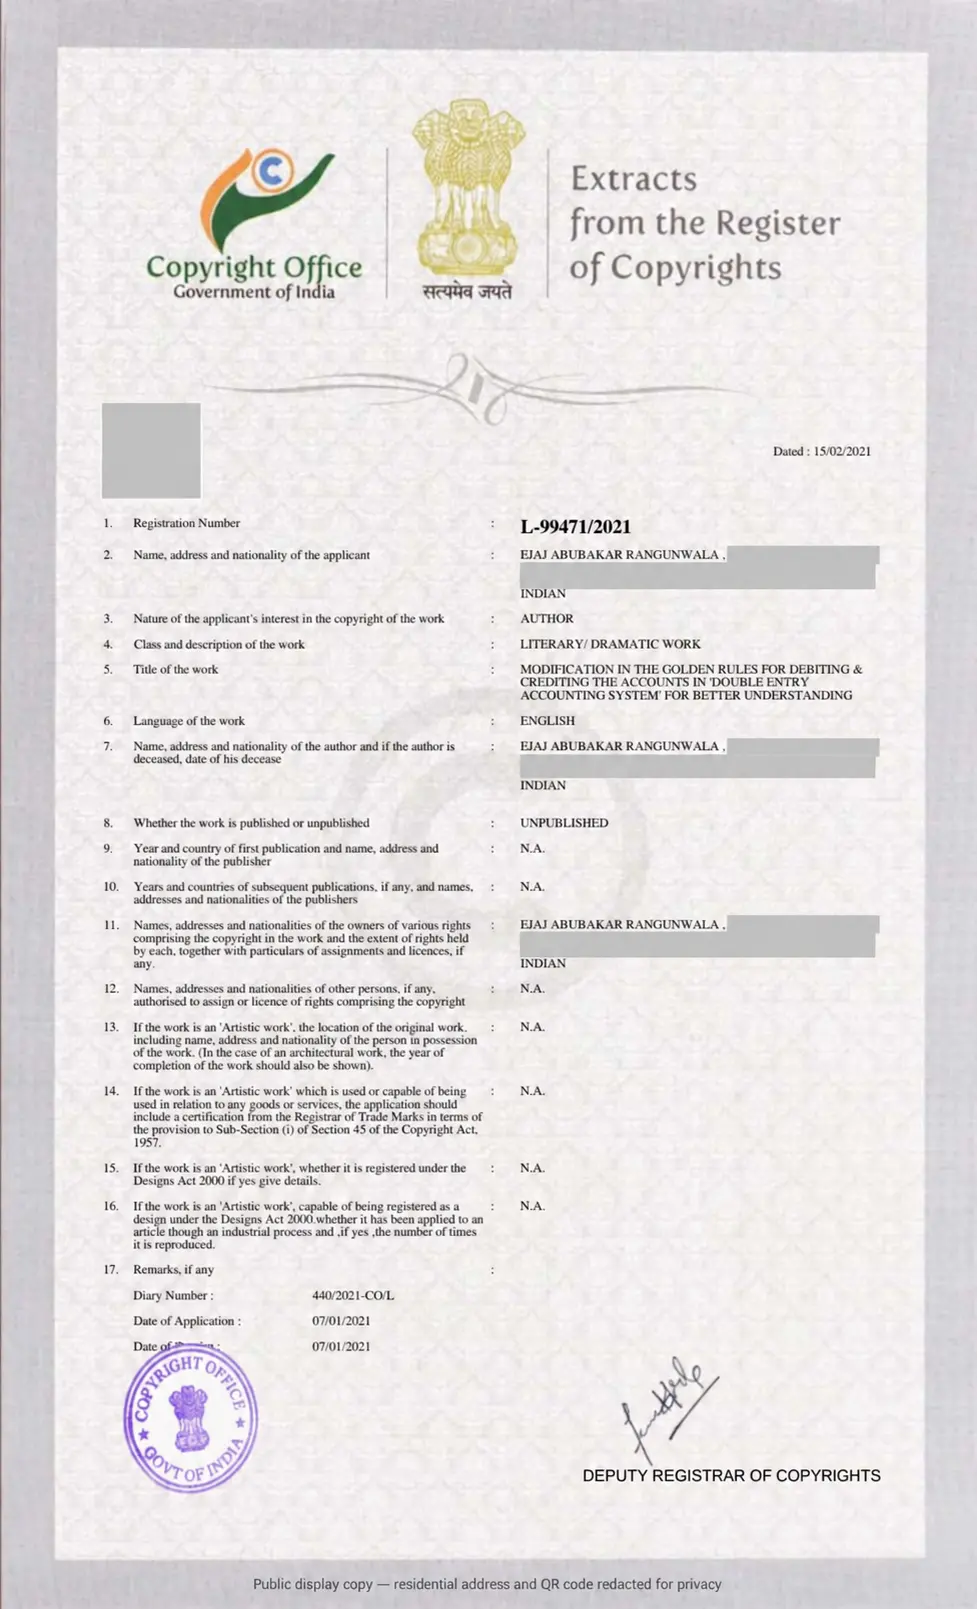
All rights reserved. Educational reference and discussion do not transfer ownership or licensing rights.
Frequently asked questions
What are the Modified Golden Rules of Accounting?
They are clarified debit-and-credit rules for Personal and Real Accounts, combined with the established Nominal Account rule, to help learners apply double-entry accounting through logic.
Who developed this framework?
The framework was developed by commerce educator and author Ejaj Abubakar Rangunwala and is presented by Rangunwala Academy.
Do the modified rules replace double-entry accounting?
No. They are a teaching and application framework within the double-entry system. Every journal entry still has equal debit and credit effects.
How are assets understood in this framework?
Assets consist of properties classified as Real Accounts and receivables classified as Personal Accounts.
Licensing and Institutional Use
Rights status: Copyright in this article and the Modified Golden Rules of Accounting remains with Ejaj Abubakar Rangunwala. Public access to this page does not transfer, assign or license any right.
Educational publishers, schools, colleges, teacher-training providers and digital-learning partners may submit a proposal for publication, translation, curriculum-resource, institutional teaching, workshop or digital-learning use.
What a serious proposal should specify
- The exact rights requested, including format, language, territory and term.
- The intended learners, institutions, distribution channels and expected reach.
- The proposed commercial model, reporting method and payment terms.
- How author attribution, content integrity and approval of adaptations will be protected.
Any arrangement is subject to written agreement, verification of rights, and appropriate legal and tax review. No licence or permission is granted merely by sending an enquiry.
Continue learning
New to the framework? Start with the checked foundation lesson Why Businesses Need Accounting, then study Types of Accounts before applying Debit and Credit rules. This sequence keeps the business event, account classification and rule application separate.
© Ejaj Abubakar Rangunwala · Published by Rangunwala Academy · All rights reserved.